Plot Loan in Hyderabad 2026: What Banks Lend on an Open Plot, Which Layouts Qualify and the Tax Position
You have found a plot you like, the seller wants a token advance this week, and the bank has just asked whether the layout is approved. That question decides whether you get a loan at all. This guide explains how a plot loan in Hyderabad works in 2026, what the rules and lenders actually say, and how to avoid paying an advance on a plot no bank will touch.
Plot loan in Hyderabad in short
Key takeaways
- ✓RBI lets banks finance a plot only if you declare that you will build a house on it within a period the bank sets (RBI Master Circular on Housing Finance, 1 April 2025).
- ✓RBI caps lending at 90% of value for loans up to ₹30 lakh, 80% up to ₹75 lakh and 75% above, and stamp duty and registration are excluded from the value.
- ✓Lenders publish lower plot limits: HDFC Bank says funding may be restricted to 70% for plots outside city limits, and ICICI Bank lends up to 80% (bank pages checked 17 October 2026).
- ✓A plot-only loan earns no tax deduction. Interest becomes deductible only once the house is built, under Section 22 of the Income-tax Act, 2025, in force since 1 April 2026.
- ✓Time matters: a home loan sanction letter usually stays valid for up to six months (Axis Bank, read 22 October 2026), so start the legal checks before you pay an advance.
Can you get a plot loan in Hyderabad?
Yes, if the plot is meant for a home. RBI’s Master Circular on Housing Finance says bank finance “can be granted only for purchase of a plot” when the borrower declares an intention to build a house on it, “with the help of bank finance or otherwise, within such period as may be laid down by the banks themselves”. RBI has since issued consolidated Credit Facilities Directions for banks (28 November 2025, updated 1 October 2026), so ask your lender for its current policy in writing.
In practice, each bank sets its own build-by deadline. When we checked the lenders’ own pages on 17 October 2026, they read as follows:
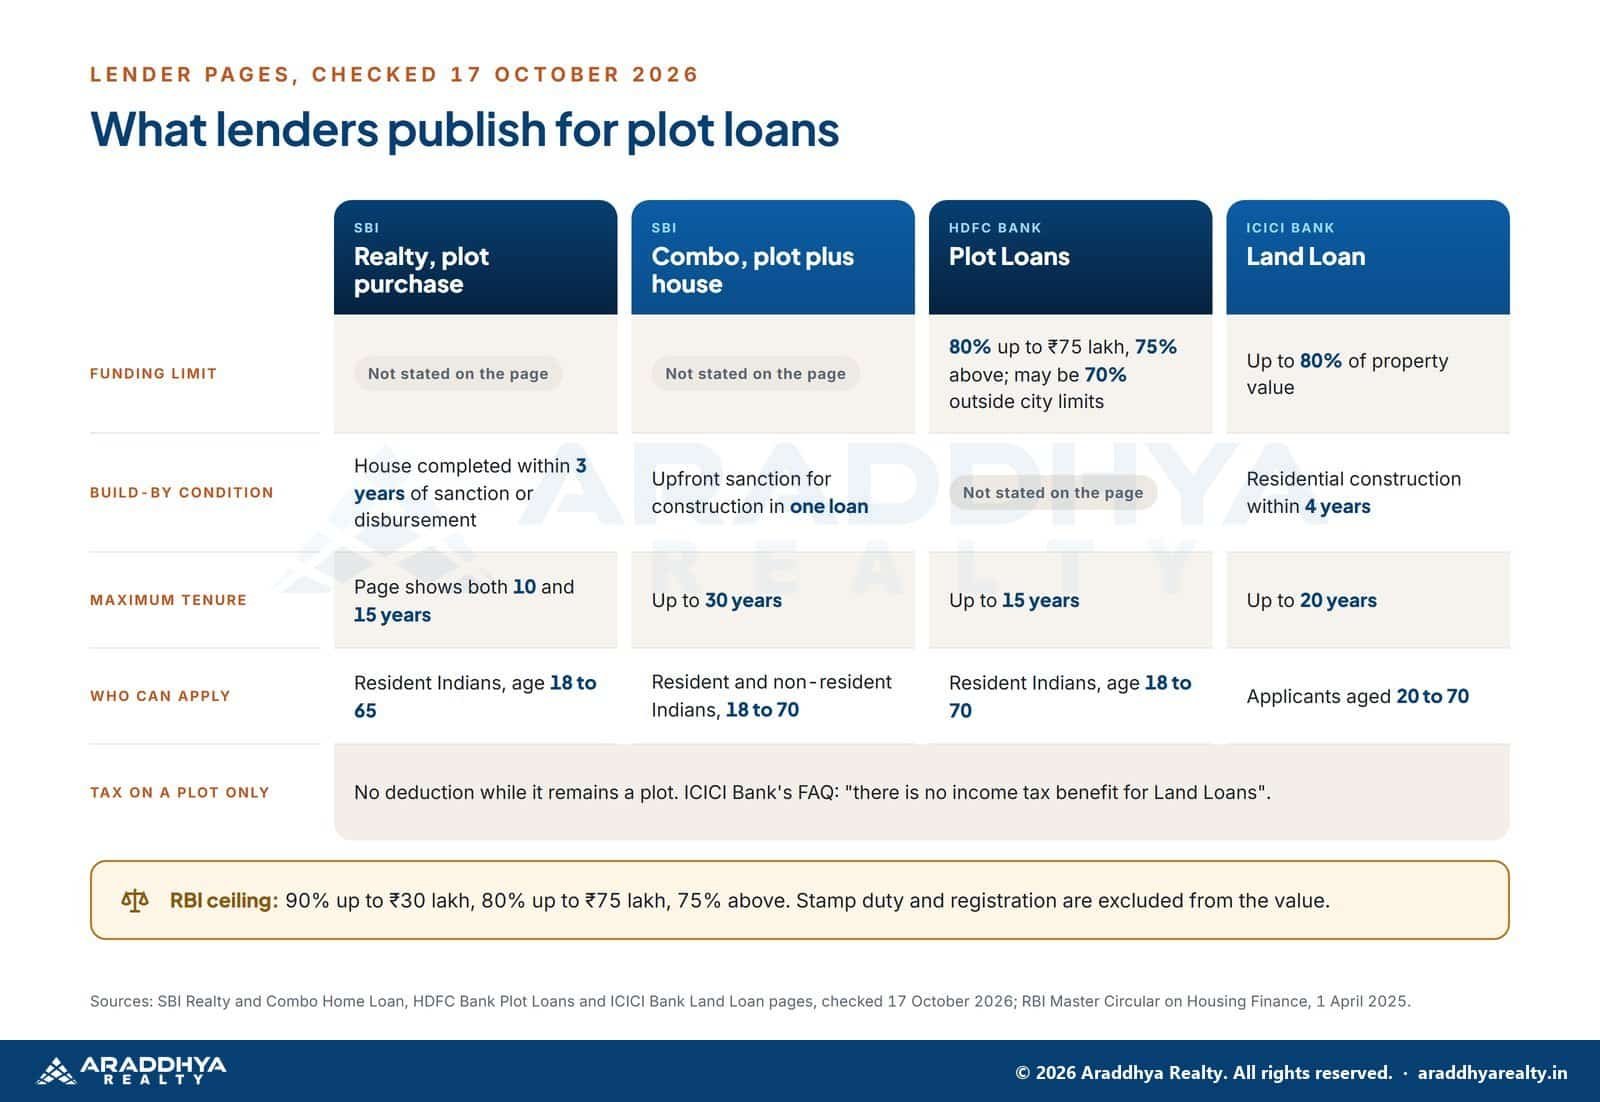
| Lender and product | Build-by condition | Maximum tenure | Who can apply |
|---|---|---|---|
| SBI Realty, plot purchase | House completed within 3 years of sanction or disbursement | Page shows both 10 and 15 years | Resident Indians, 18 to 65 |
| SBI Combo Home Loan, plot plus construction | One composite loan with upfront sanction for building | Up to 30 years | Resident and non-resident Indians, 18 to 70 |
| HDFC Bank Plot Loans | Not stated on the page | Up to 15 years | Resident Indians, 18 to 70 |
| ICICI Bank Land Loan | Residential construction within 4 years | Up to 20 years | Applicants aged 20 to 70 |
These are starting points, not offers; read the SBI Realty, HDFC Bank and ICICI Bank pages for the full terms.
How much will a bank lend on a plot?
Two limits apply. The first is RBI’s loan-to-value (LTV) ceiling for housing loans. The second, usually lower, is the lender’s own plot policy.
| Loan size | RBI LTV ceiling for housing loans | What lenders publish for plots, October 2026 |
|---|---|---|
| Up to ₹30 lakh | 90% | HDFC Bank 80%; ICICI Bank up to 80% |
| ₹30 lakh to ₹75 lakh | 80% | HDFC Bank 80%; ICICI Bank up to 80% |
| Above ₹75 lakh | 75% | HDFC Bank 75% |
HDFC Bank’s page adds two conditions that matter in South Hyderabad. Funding is “subject to market value of the plot”, and it “may be restricted up to 70%” if the plot is outside city limits. Many layouts in Kandukur and Maheshwaram mandals sit in gram panchayat villages outside the city, so plan your budget at 70% and treat anything higher as a bonus.
Then there is registration. RBI tells banks not to include stamp duty, registration and documentation charges in the property cost, except where the cost is ₹10 lakh or less. In Telangana, a plot sale deed costs 7.5% of the higher of the deal value and the government market value, and market values were revised statewide from 5 June 2026. That 7.5% comes from your own pocket.
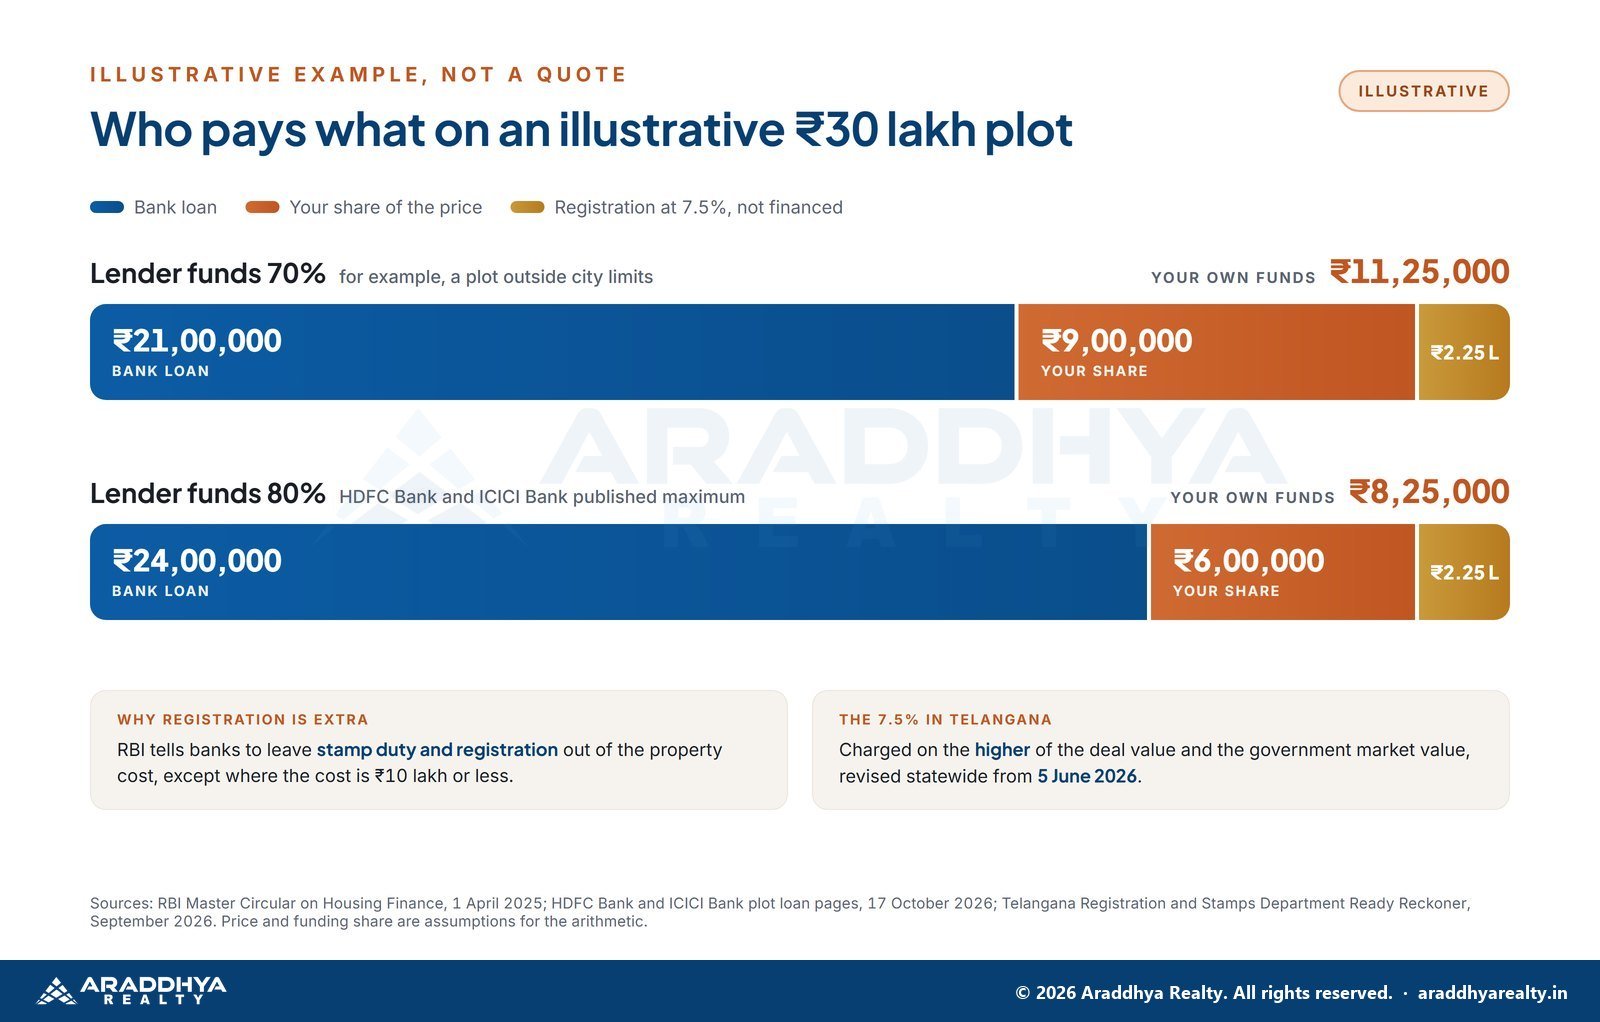
| Illustrative ₹30 lakh plot | At 70% funding | At 80% funding |
|---|---|---|
| Bank loan | ₹21,00,000 | ₹24,00,000 |
| Your share of the price | ₹9,00,000 | ₹6,00,000 |
| Registration at 7.5% | ₹2,25,000 | ₹2,25,000 |
| Your own funds | ₹11,25,000 | ₹8,25,000 |
These figures are an assumption for the arithmetic, not a quote for any plot. Our guide to plot registration charges in Telangana works through the 7.5% in detail.
Which plots and layouts banks will finance
Banks lend against the plot, so they examine it as closely as they examine you. RBI’s master circular tells banks to ensure the borrower has “prior permission from government / local governments / other statutory authorities” wherever required, and to release money only after those clearances exist. For an open plot near Hyderabad, that comes down to four things.
- An approved layout. The layout should carry a layout permission (LP) number from the authority for that village: HMDA in the metropolitan region, FCDA in the 56 villages notified on 12 March 2025, or DTCP elsewhere. Our explainer on HMDA vs DTCP approval shows how to tell which applies.
- A clean chain of title. HDFC Bank asks for “Title Deeds including the previous chain of the property documents in resale cases”. The bank’s lawyer reads the same link documents and encumbrance certificate you should read first, listed in our clear title checklist.
- Residential, not agricultural, land. Lenders finance residential plots. Telangana also does not register farm plots below 2,000 sq m, so a “farm plot” sold in small pieces is a poor candidate for a loan.
- A plot the valuer can value. The bank’s valuer sets its own figure, and a valuation below your price means a smaller loan.
One local wrinkle deserves a word. Villages that moved to FCDA in March 2025, such as Mohammadnagar in Kandukur mandal, may hold layouts approved earlier by HMDA. Such permissions can be genuine, but expect the bank’s lawyer to ask for the LP copy and to confirm it with the authority that issued it. Pulimamidi, near Maheshwaram, remains in the HMDA region under G.O.Ms.No.68. Our Kandukur and Pulimamidi area pages show which authority covers each village.
Not sure a bank will lend on the plot you like? Send us the layout name and survey number and we will tell you which papers a lender’s lawyer will ask for, free.
Eligibility and the documents to prepare
Lenders decide the amount mainly on income and repaying capacity. HDFC Bank also weighs age at loan maturity and savings history, and requires all co-owners to be co-applicants; an earning co-applicant can raise the amount.
Prepare these before you pay any advance:
- Identity and address proof: PAN, plus Aadhaar, passport, voter ID or driving licence.
- Income proof if salaried: three months’ salary slips, six months’ bank statements and Form 16 with your income tax filings.
- Income proof if self-employed: two years’ income tax filings with computation, and two years’ accounts attested by a chartered accountant (HDFC Bank’s list).
- Property papers: the agreement of sale or allotment letter, the layout permission copy, the link documents and an encumbrance certificate. Our guide to the encumbrance certificate in Telangana shows how to pull one online.
- Proof of your own contribution: bank statements showing the money you are paying from your own funds.
Gathering papers on your phone? Message us on WhatsApp with the list you already have, and we will tell you which property papers a lender usually asks for next, free.
Plot plus construction: one loan or two?
You can borrow for the plot now and for the house later, or arrange both together. SBI’s Combo Home Loan covers the plot and the house “in a single composite loan” with an upfront sanction for construction, and lists a tenure of up to 30 years. HDFC Bank’s plot loan page also lists loans for construction on a freehold or leasehold plot. Either way, RBI requires a copy of the building plan sanctioned by the competent authority before a construction loan is sanctioned.
The build-by clock matters. SBI Realty asks for the house to be complete within three years of sanction or disbursement, and ICICI Bank within four years. If your plans are longer than that, discuss it with the lender before you sign.
The tax position in 2026
The Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026. For home loans, Section 22 of the new Act corresponds to the old Section 24, according to the Union Budget 2026-27 memorandum.
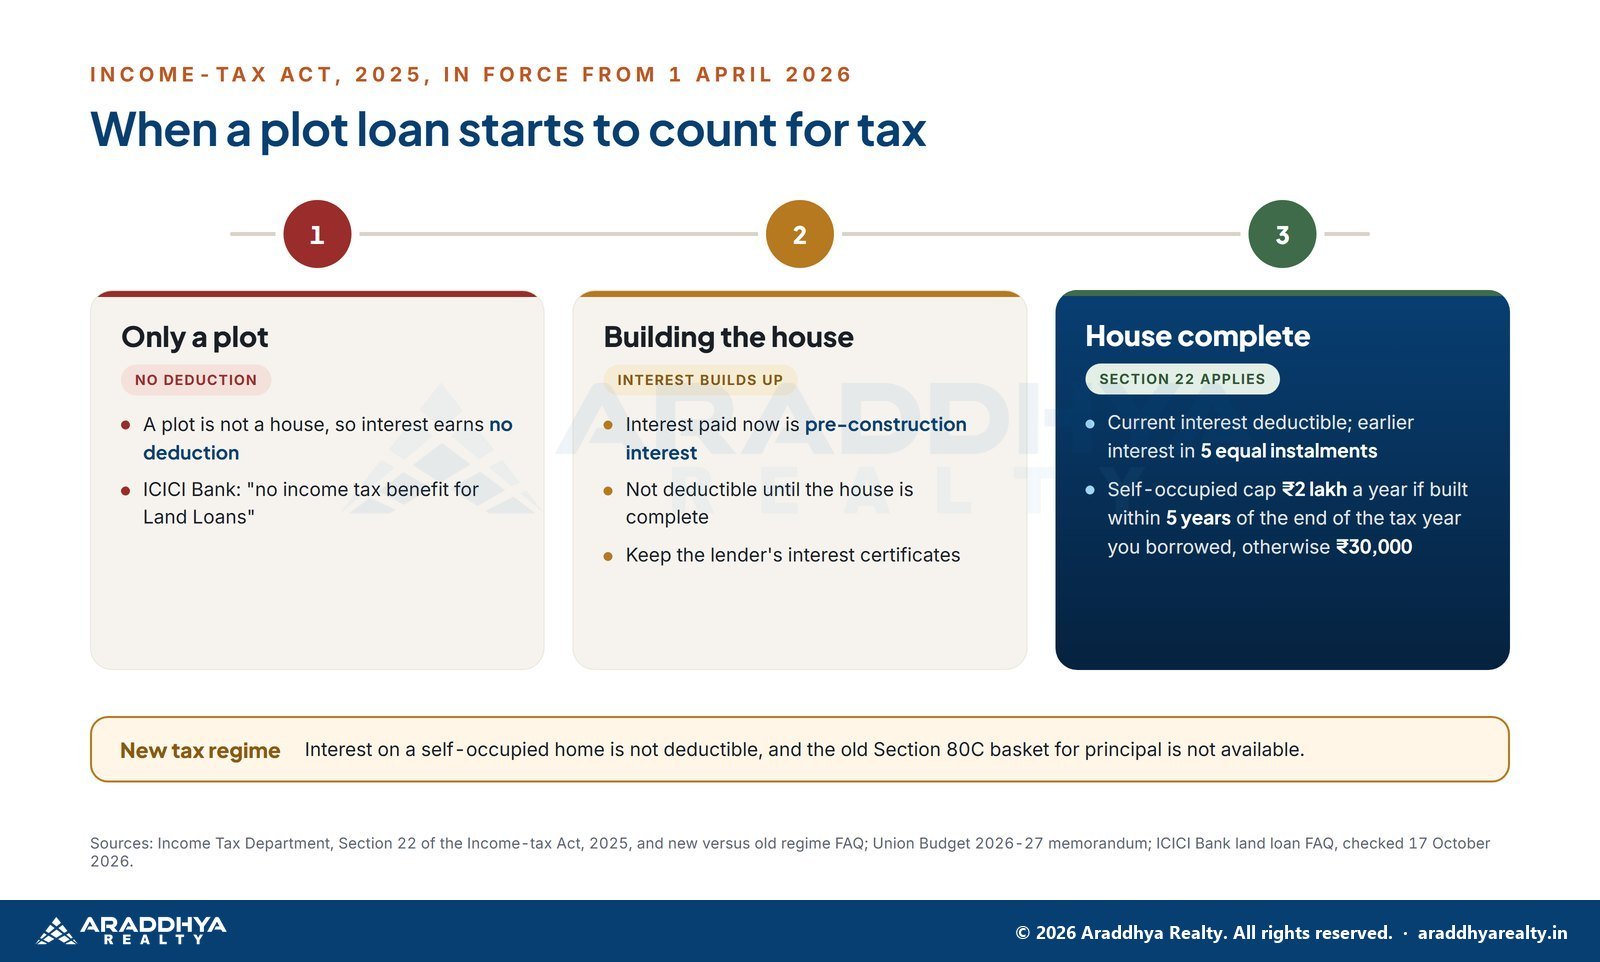
- While it is only a plot: a plot is not a house, so there is no interest deduction. ICICI Bank’s own FAQ says “there is no income tax benefit for Land Loans”.
- Once the house is complete: interest on money borrowed to acquire or construct the house is deductible. Interest paid before completion is allowed in five equal instalments from the year of completion.
- The cap for a home you live in: ₹2 lakh a year, but only if construction finishes within five years from the end of the tax year in which you borrowed; otherwise ₹30,000. The Finance Bill 2026 proposed counting the pre-construction instalments inside that ₹2 lakh.
- The regime you choose: under the new tax regime, the Income Tax Department’s regime FAQ says interest on a self-occupied property is not deductible, and the old Section 80C basket for principal is also unavailable.
Whether interest on the plot part of a composite loan counts as pre-construction interest is a question for your tax adviser.
Why starting your loan file early matters
Most plot loans that go wrong fail on time, not income. None of what follows depends on where land values go.
- Checks take days to weeks. The encumbrance certificate, the Bhu Bharati record, the layout permission check and the bank’s legal and valuation reports often run one after another. A late starter is the buyer pressed for an advance before the bank’s lawyer has finished, and an advance is hard to recover if the title fails.
- A sanction letter has a shelf life. Axis Bank’s guide says validity usually lasts up to six months from issue, varying by lender. Plan registration inside the date printed on yours.
- Registration follows the value on the day you register. The 7.5% is charged on the higher of the deal value and the market value on the registration date. The Ready Reckoner links market value orders of 20 July 2021 and 21 January 2022, and values were revised statewide again from 5 June 2026. No next revision has been announced, but a deed registered after any revision pays on the new value; our guide to checking the market value online shows where to look.
- Older layouts have a deadline. The 25% LRS rebate for 2020 applicants was reported extended to 30 November 2026 (Deccan Chronicle, 1 August 2026), and a lender will want regularisation settled first. See LRS and BRS in Telangana in 2026.
- Choice narrows as plots are booked. East-facing, corner and park-facing plots are usually chosen first in any layout, so a buyer with papers ready chooses on the visit.
Illustrative: Kavya and Suresh, both teachers, chose a plot in March but began the loan papers in June. When the bank’s legal report arrived, the plot had gone to a buyer with a sanction letter, and building before their daughter’s first school year slipped by twelve months: another year of rent for paperwork they could have started in March.
What is changing around the south Hyderabad belt (status as of October 2026)
Most loan buyers we meet are looking along the Srisailam Highway (NH-765) and in the Future City belt. Here is the dated status of what is being built around them.
| Project | What it is | Status | Date / source |
|---|---|---|---|
| Bharat Future City and FCDA | Planning authority, 56 villages | Operational; master plan in preparation | G.O.Ms.No.69, 12 March 2025; plan due at the 7 to 9 December 2026 summit (Deccan Chronicle, 13 October 2026) |
| Young India Skills University, Meerkhanpet | Permanent campus | Under construction | Chief Minister’s review, 19 October 2026 (Deccan Chronicle) |
| Ratan Tata Greenfield Radial Road | 41.5 km, 100 m corridor, ORR Exit 13 to Amangal | Under construction | HMDA target May 2028 (Swarajya, 9 September 2026) |
| AWS data centre | Campus in Bharat Future City | Under construction | Foundation stone 15 July 2026 |
| Airport to Future City metro | 39.6 km line | Proposed; awaiting central approval | Swarajya, 7 May 2026 |
| Regional Ring Road, northern part | 161.5 km, Sangareddy to Choutuppal | Announced; not under construction | Fresh tenders due (Deccan Chronicle, 9 October 2026) |
| Regional Ring Road, southern part | 201 km, via Amangal | Proposed; no central decision | Deccan Chronicle, 24 September 2026 |
| E-City and Fab City, Raviryal | Electronics and industrial parks | Operational | Units operating, July 2026 (The Hans India) |
For a loan buyer this is about time and distance. Today’s jobs are at E-City, Fab City and nearby industrial parks; the Future City employers are under construction with no published opening dates. Schools, hospitals and shops usually follow homes and jobs over years, so plan on Kandukur, Maheshwaram town or the city at first. With a build-by deadline of three or four years, plan the house around roads that are built today: NH-765 and the ORR.
From Araddhya Future City at Mohammadnagar, Mucherla measured 16 minutes (11.2 km), ORR Exit 14 24 minutes and RGI Airport 32 minutes (23.5 km). From Sai Krishna Vrinda at Pulimamidi, Mucherla measured 24 minutes and the airport 36 minutes (23.9 km), on Google Maps on 14 September 2026. Our Future City development tracker and guide to the southern growth corridors follow each project.
What this means if you are buying a plot
Here is an illustrative scenario. Ravi and Sunitha, both salaried, shortlisted two plots on the Srisailam Highway. The cheaper one came with a photocopied layout map and a promise that “approval is coming”, and the bank’s lawyer would not proceed. The second had an LP number they could check, a full chain of title and an encumbrance certificate, and the file moved. The relief was knowing the papers would survive a lender’s scrutiny, and a future buyer’s.
That is why we steer loan buyers to approved layouts first. Both ventures we show list an HMDA layout permission on their project pages: Araddhya Future City at Mohammadnagar, Kandukur, and Sai Krishna Vrinda at Pulimamidi, near Maheshwaram, both on the NH-765 corridor. The Araddhya Future City page states that we assist with the complete loan file at no extra charge. Whether a bank lends, and how much, is always the lender’s decision.
Want to walk the layouts before you speak to a bank? Take the 360° virtual tour of both ventures, then bring your lender’s questions to the site.
Ask for the agreement to make the sale subject to sanction. Once the sale deed is signed, Telangana allows four months to present it for registration, and later presentation carries a penalty.
Your next step
- Ask your bank, in writing, for its plot funding limit, build-by period and sanction validity.
- Confirm the layout permission number with the authority that issued it.
- Pull the encumbrance certificate and the Bhu Bharati record.
- Budget your share of the price plus 7.5% registration from your own funds.
- Make the agreement subject to loan sanction before any advance.
This guide is general information, not financial, tax or legal advice. Loan terms, rates and rules change, and every lender assesses each case separately. Confirm the current terms in writing with the lender, and take advice from a chartered accountant on your tax position and an advocate on the title.
There is a particular relief in a sanction letter that comes back with no queries on the title. It means the papers have already passed their hardest reader, and that the house you sketched on the back of the agreement can be built. That is the moment we work towards with every family that buys with a loan.
Plan your next step
Planning to buy a plot with a bank loan? Araddhya Realty is a TG-RERA registered agent (A02500007890). Tell us your budget, your timeline and how you earn, and we will shortlist approved plots with the papers a lender asks for, then help you put the loan file together at no extra charge. Tell us your budget and timeline. Prefer WhatsApp? Message us on WhatsApp.
Frequently asked questions
Yes, for a residential plot in an approved layout, if you declare that you will build a house on it within the period the bank sets. RBI’s housing finance rules allow plot finance on that condition. Lenders such as SBI, HDFC Bank and ICICI Bank publish plot loan products, but each makes its own credit and legal assessment.
RBI caps housing loans at 90% of value up to ₹30 lakh, 80% up to ₹75 lakh and 75% above. Lenders publish lower limits for plots: HDFC Bank 80% or 75%, restricted to 70% outside city limits, and ICICI Bank up to 80%, as checked on 17 October 2026.
Not while the land remains an empty plot. Under Section 22 of the Income-tax Act, 2025, interest becomes deductible once the house is built, with pre-construction interest spread over five years. Under the new tax regime, interest on a self-occupied home is not deductible at all.
It depends on the lender. SBI’s Realty page asks for the house to be complete within three years of sanction or disbursement, and ICICI Bank’s land loan within four years. RBI leaves the period to each bank, so check the sanction letter before you sign.
You should not expect it. RBI asks banks to confirm that required government permissions exist before releasing money, and lenders examine the layout permission and title chain. A layout awaiting regularisation is also a risk to you as owner, so resolve the approval before paying an advance.
Yes. SBI’s Combo Home Loan combines plot purchase and construction in one composite loan with an upfront sanction, and HDFC Bank lists loans for construction on a freehold or leasehold plot. Construction finance needs a building plan sanctioned by the competent authority before the loan is sanctioned.
Neither has a date to plan around. The airport to Future City metro was proposed and awaiting central approval in May 2026, and the southern RRR had no central decision on 24 September 2026. Lenders assess the plot and your income as they stand today, so decide on built roads and checked approvals, and verify any project a seller cites.
Sources. RBI Master Circular on Housing Finance, 1 April 2025, and Credit Facilities Directions, updated 1 October 2026, read 17 October 2026 · SBI Realty, SBI Combo, HDFC Bank and ICICI Bank pages, read 17 October 2026 · Axis Bank sanction letter guide, read 22 October 2026 · Income Tax Department: Income-tax Act, 2025; Section 22; regime FAQ, read 17 October 2026 · Union Budget 2026-27 memorandum, February 2026 · Ready Reckoner, read 17 October 2026; market values from 5 June 2026 · G.O.Ms.No.68 and G.O.Ms.No.69, 12 March 2025 · Deccan Chronicle: LRS rebate, 1 August 2026; master plan and summit, 13 October 2026; Skills University review, 19 October 2026; RRR north, 9 October 2026; RRR south, 24 September 2026 · Swarajya: Ratan Tata Road, 9 September 2026; metro, 7 May 2026 · The News Minute, AWS, 16 July 2026 · The Hans India, E-City, 28 July 2026 · Google Maps, 14 September 2026 · Project pages, read 22 October 2026.
This article is general information, not investment or legal advice. Figures are dated and change often. Verify approvals and project registration yourself at rera.telangana.gov.in and with the issuing planning authority before any purchase.
Useful next reads. the ten checks before you pay; how the southern corridors compare; which approval applies where; how to test a brochure claim; areas we cover; buyer questions answered; all our guides.
Disclaimer · Privacy policy · Terms of use · Araddhya Realty home